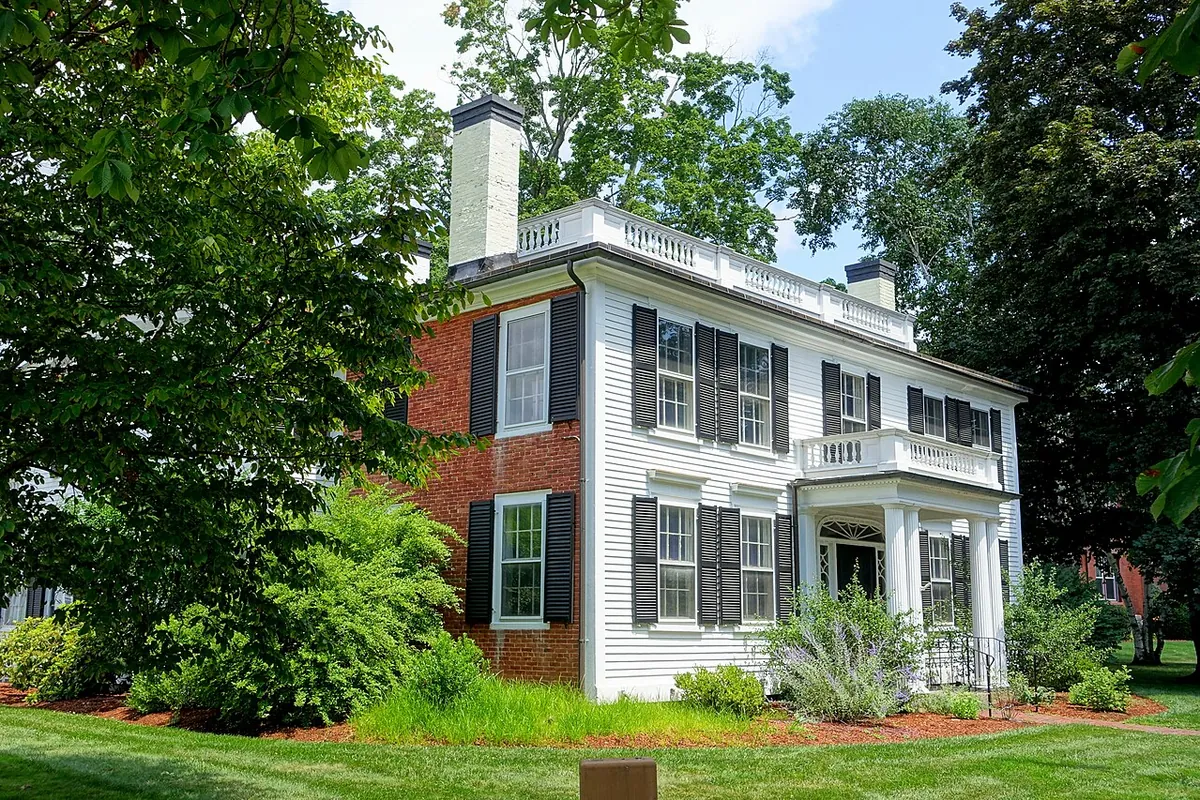
The house shapes the claim
New Hampshire’s housing stock runs from 18th-century farmhouses to vinyl-sided subdivisions finished last spring. Carrier estimating software treats a wall as a wall. In practice, the age and construction of the house drive most of the arguments we see.
Older colonials and farmhouses
Plaster on lath, wide-board pine floors, hand-run trim, balloon framing and attached ells that grew one barn at a time. A desk adjuster who prices drywall and stock casing for a Portsmouth South End house or an Amherst village colonial is pricing a different building.
Post-war capes and ranches
These are the workhorses of Manchester, Concord and Rochester. They often carry decades of layered repairs — two roofs over one deck, knob-and-tube spliced into newer circuits — which matters once code items enter the estimate.
Newer subdivisions
In Bedford, Hooksett, Salem and Londonderry, the fight is usually about matching: discontinued siding colors, open floor plans where flooring runs through five rooms, and cabinet lines that changed two years after closing.
Where house estimates tend to come up short
| Issue | What we often see | What we check |
|---|---|---|
| Scope | Only the visibly stained ceiling is priced | Insulation, framing, adjacent rooms, the floor above |
| Matching | Partial replacement of a continuous surface | Policy wording and whether a reasonable match exists |
| Pricing | Labor rates that don’t reflect your region | Current local costs, trip charges for remote towns |
| Code items | Left out or deferred without explanation | Ordinance or law coverage and local permit requirements |
| Overhead & profit | Omitted on jobs needing several trades | Whether a general contractor is reasonably needed |
Replacement cost and the second check
Many New Hampshire homeowners policies pay actual cash value first and release the depreciation holdback once repairs are done. That means the depreciation column matters twice: once for the first check, and again for whether you can afford to start work at all. Our depreciation holdback planner helps you see the gap before you sign a contract. Some policies also set a time limit for completing repairs to collect the holdback — check yours.
Town by town, the costs differ
A roofer in Nashua might be booked three weeks out; a roofer willing to drive to Pittsburg or Colebrook in November may add travel days. Permit fees, dumpster availability and lumber delivery all change across the state. We price the job where it sits — whether that is a Nashua triple-decker or a seasonal place on the far side of the Mount Washington Valley.
Don’t forget what stands apart from the house. Detached garages, sheds, barns and stone-walled outbuildings usually fall under an “other structures” limit, often a set share of the dwelling limit. On an old Sullivan County farm, the connected barn can raise its own question: is it part of the dwelling or a separate structure? The answer can change which limit applies, so we read the declarations before scoping it.
Before you invoke appraisal
- Ask the carrier for its complete estimate, including the line-item report, not just a summary.
- Write down what you believe is missing and send it in as a supplement request.
- Keep receipts for emergency work, tarps and temporary heat.
- If the gap remains, read your appraisal clause and talk to us about whether the numbers justify the process.
Our gap and fee estimator gives a rough sense of whether appraisal is worth the cost on your claim.
What owners ask about this
Is appraisal worth it on a smaller house claim?
It depends on the size of the gap relative to the cost of the process. When the difference is a few hundred dollars, a well-documented supplement request is often the better first step.
Will the insurer cancel my policy if I invoke appraisal?
Appraisal is a right written into many policies. Renewal decisions involve many factors; if you’re concerned, ask the New Hampshire Insurance Department or an attorney about the rules that apply.
Do you handle condo unit owner claims?
Yes. HO-6 unit owner claims often overlap with the association’s master policy, so we review both to see which one should pay for what.