Independent appraisal · All 10 counties
New Hampshire Insurance Appraiser for claims the insurer underpaid
Your insurer accepted the claim, but the check won’t cover the work. New Hampshire Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal clause in your policy.
- Your appointed appraiser
- Homes, condos & commercial
- Fee in writing up front
Where the money goes missing
The gap is usually in the line items, not the headline
Most short claims aren’t denials. They’re estimates with a slope left off, ice & water shield priced at the eaves only, a ceiling painted but not the room, or overhead and profit left out. A New Hampshire Insurance Appraiser finds those lines, measures them and prices them so they hold up in front of an umpire.
The ledger shows the kind of differences we look for. It’s an illustrative example, not a client file.
About estimate auditsIllustrative figures only. Every claim depends on its own policy, damage and pricing.
What we appraise
A dozen claim types, one independent New Hampshire Insurance Appraiser
Bring us in for a single estimate audit, as your appointed appraiser once appraisal is demanded, or as a neutral umpire.
 Most asked about
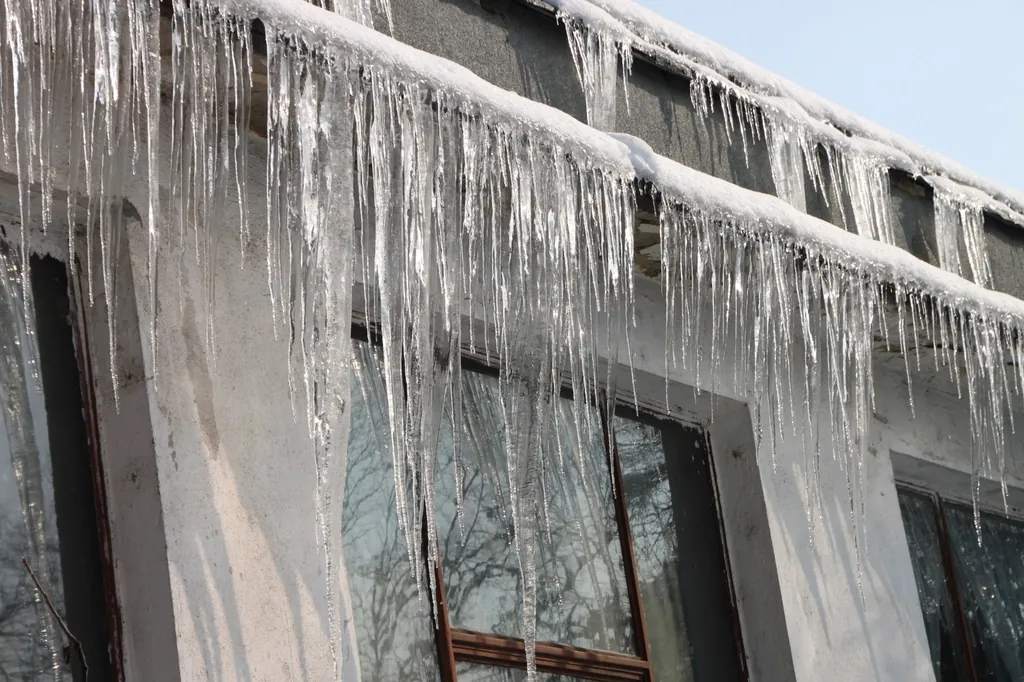
Ice Dams & Heavy Roof Snow
Ice dam leaks, roof snow load and collapse claims — New Hampshire’s signature winter losses, valued in full.
Learn more Core service
Policyholder’s Appraiser on the Panel
We act as the appraiser you appoint when your policy’s appraisal clause is invoked on a New Hampshire claim.
Learn more Service
Single-Family Home Claims
Capes, colonials, ranches and new builds — independent valuation when the carrier’s house estimate falls short.
Learn more Service
Condo, Association & Business Claims
Mill conversions, condo associations, multifamily and main-street storefronts with complex scopes and shared walls.
Learn more Service
Roof Damage & Hail Disputes
Hail, wind and storm roof losses where the carrier priced patches, missed slopes or skipped New Hampshire code items.
Learn more Service
Microburst & Windstorm Losses
Straight-line winds, microbursts and the occasional tornado — when the carrier’s wind scope stops at the obvious.
Learn more Service
Tropical Remnants & Coastal Storms
Tropical remnants and nor’easter wind on the Seacoast and inland — with honest talk about what policies cover.
Learn more Service
Frozen Pipe & Leak Claims
Frozen pipes, failed boilers and slow leaks in homes and seasonal camps — valued with the hidden damage included.
Learn more Service
Chimney, Fire & Smoke Losses
Chimney fires, woodstove incidents, kitchen fires and full losses — with smoke and soot scope valued properly.
Learn more Service
Trees Down on the Property
Pines through the roof, oaks across the garage — valued with structural damage, removal and cleanup included.
Learn more Service
Line-by-Line Estimate Audit
A line-by-line review of the carrier’s estimate so you know what is missing before you sign or invoke appraisal.
Learn more Service
Neutral Umpire Appointments
Neutral umpire services for New Hampshire appraisal panels when the two appraisers can’t reach agreement.
Learn moreA year of claims
Twelve months of New Hampshire weather, twelve kinds of file
Winter writes the most files, but every month brings something. Darker months are when a New Hampshire Insurance Appraiser hears from the most owners.
- JanIce damsFrozen pipes
- FebRoof snow loadIce dams
- MarNor’eastersSnowmelt leaks
- AprSpring floodsThaw leaks
- MayWindHail
- JunHailLightning
- JulMicroburstsHail
- AugTropical remnantsFlash floods
- SepTropical stormsWind
- OctEarly snowWindstorms
- NovChimney firesWind
- DecIce stormsWind & rain
How it works
The appraisal clause, one step at a time
The appraisal clause swaps an open-ended argument for a defined process. Here’s how New Hampshire Insurance Appraiser moves a file through it.
- 1
Read the file
Policy, declarations, the insurer’s estimate and your photos — then a plain answer on whether appraisal fits.
- 2
Re-scope the loss
Our own inspection and measurements, priced line by line for your part of New Hampshire.
- 3
Invoke the clause in writing
Appraisal is invoked under your policy, and your appraiser is named within its time limits.
- 4
Reconcile line by line
Line-by-line work with the insurer’s appraiser. Most of the gap is usually settled here.
- 5
Two signatures, one award
Anything left goes to a neutral umpire. Two signatures set the amount of loss.
Regional knowledge
From the Seacoast to the North Country
Salt wind on the Seacoast, frozen camps on Winnipesaukee, snow-loaded condos below Mount Washington. A New Hampshire Insurance Appraiser has to know how each one shows up in an estimate.
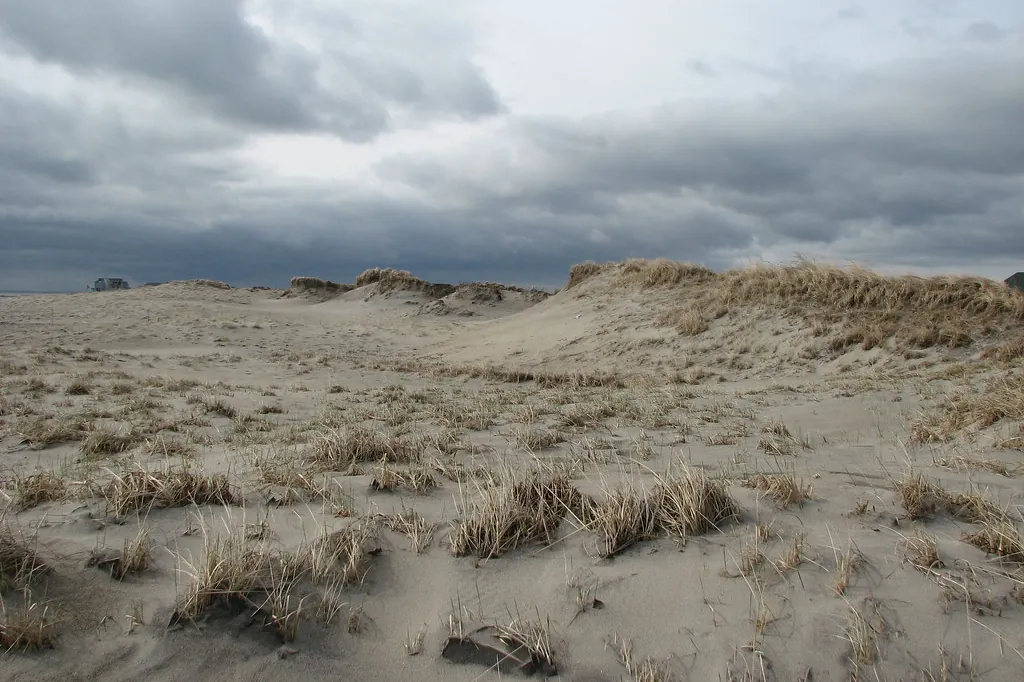
Seacoast
Eighteen miles of coastline, the Piscataqua River and Great Bay. Older homes in Portsmouth’s South End and Exeter meet newer subdivisions inland, and nor’easters test both.
- Nor’easter wind
- Wind-driven rain
- Salt-air wear disputes
- Historic homes
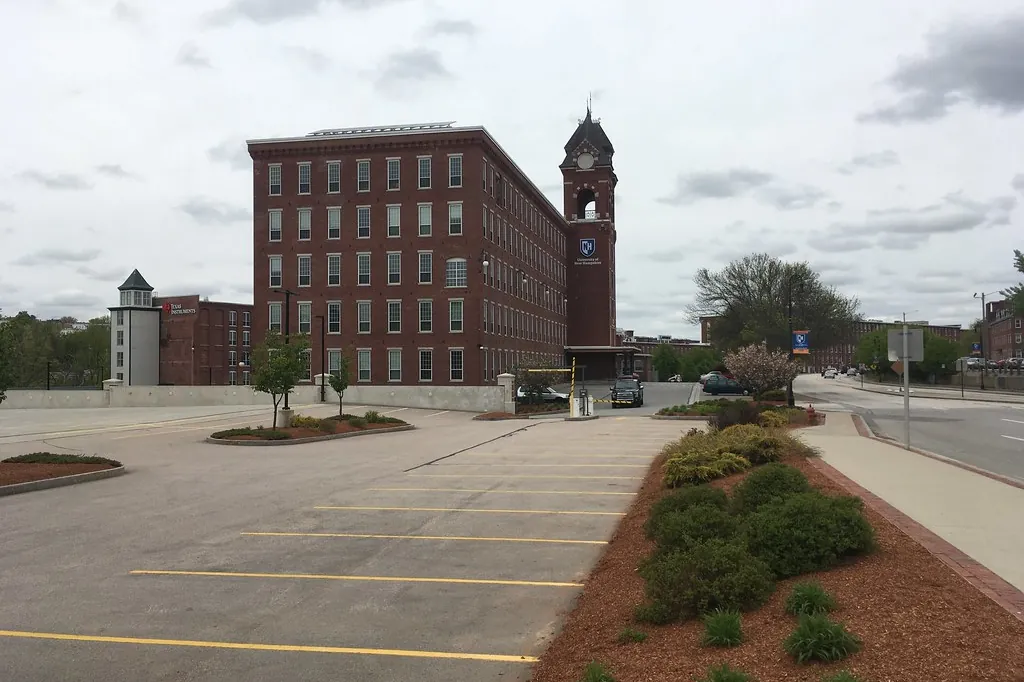
Merrimack Valley
The state’s population center. Summer storms track across Hillsborough and Merrimack counties, and multi-unit buildings turn one frozen pipe into several claims.
- Microbursts & hail
- Burst pipes in multifamily
- Tree fall
- Mill-condo losses
Lakes Region
Lake Winnipesaukee’s shoreline is lined with seasonal camps that sit empty for months. Freeze-ups found in spring and ice damage to waterfront structures lead the claim list.
- Vacant-camp freeze-ups
- Ice dams
- Docks & boathouses
- Ice storms
Monadnock & Upper Valley
Brick downtowns, river valleys and college-town rentals. Heavy wet snow and river flooding have both left their mark on Cheshire and Grafton counties.
- River flooding
- Snow load
- Rental & campus housing
- Downed hardwoods
White Mountains & North Country
Elevation, deep snowpack and steep valleys. Carroll and Coös county claims often involve condominium associations, snow-load framing damage and storm runoff.
- Roof snow load
- Ski-condo HOA claims
- Ice storms
- Flash flooding
Quick check
Run your two numbers before you call
Type in the two numbers you already have. If the difference is large, talking with a New Hampshire Insurance Appraiser makes sense. If it’s small, a documented supplement request may close it faster.
The full dispute size & net recovery estimator adds appraiser and umpire fees.
Free and private
Seven calculators, built from appraisal files
Run the numbers before you call anyone. Each tool runs in your browser, and nothing you type is stored or sent.
 ΔCalculator
Dispute Size & Net Recovery Estimator
Size the disputed amount, test where an award might land and subtract appraiser and umpire fees.
ACVPlannerTwo-Check Holdback Planner
List items with age and life to split a claim into the first ACV payment and the depreciation held back.
 ▲Calculator
Steep-Roof Squares Checker
Turn a footprint and pitch into true roof squares, bundles and steep-roof flags to check an estimate.
 %Calculator
Percent-to-Dollars Deductible Tool
Convert a percentage wind or named-storm deductible into dollars and compare it with a flat deductible.
 ◷Planner
Granite State Claim Clock
Map notice, proof of loss, depreciation and suit dates from your date of loss, then export them.
 ✓Checklist
Claim File Readiness Gauge
Twelve yes-or-no questions that score your claim file and build a to-do list before you demand appraisal.
 ❄Calculator
Snow Weight Roof Calculator
Estimate how much the snow and ice on your roof weighs, and compare it with a benchmark you enter.
On the record
The storms behind today’s claim arguments
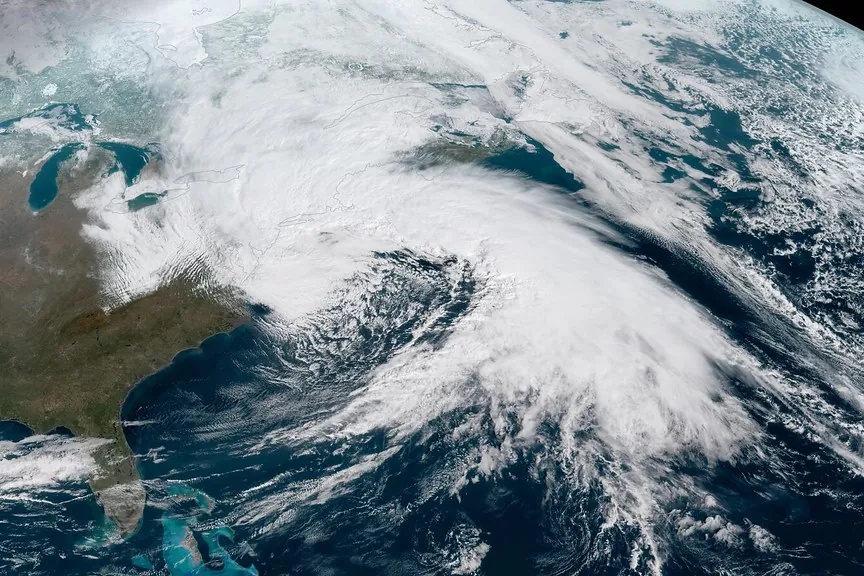
Older storms set the patterns adjusters and appraisers still argue about: what counts as wind versus flood, how ice damage is scoped, when a tree-on-roof claim includes the tree. A New Hampshire Insurance Appraiser reads every file with that history in mind.
- 1938
The Great Hurricane of ’38
Still the benchmark for wind damage in the state — a reminder that inland New Hampshire can see hurricane-force gusts.
- 1998
North Country ice storm
Ice-loaded limbs across the North Country and Lakes Region. Tree-fall and roof-impact claims dominated.
- 2006
Mother’s Day floods
Days of rain swelled rivers in the Lakes Region and Seacoast, separating flood-policy losses from homeowners claims.
- 2008
Deerfield tornado & December ice storm
A rare EF2 tornado in July, then an ice storm that left hundreds of thousands without power in December.
- 2011
Tropical Storm Irene & “Snowtober”
Irene’s flooding tore through White Mountain valleys; an October snowstorm then dropped heavy snow on trees still in leaf.
- 2015
Record late-winter snowpack
Weeks of accumulated snow led to ice dams, interior leaks and roof-load damage across southern New Hampshire.
- 2017
Halloween-eve windstorm
One of the largest power outages in state history and a wave of tree-on-house claims.
- 2023
December 18 wind and rain
Damaging gusts, heavy rain on frozen ground and river flooding, just before the holidays.
Statewide
Local pages for twelve New Hampshire communities
We work in every county. These are the communities where owners call us most often.
Right help, first time
Who should you call about a short claim?
Each professional solves a different problem. New Hampshire Insurance Appraiser will tell you when appraisal isn’t the right tool.
Hire an appraiser when…
Coverage accepted, amount disputed.
- Values the amount of loss
- Works inside the appraisal clause
- Result: an award signed by two of three
Hire a public adjuster when…
You want the whole claim handled.
- Prepares and negotiates the claim
- Usually best early on
- Result: a negotiated settlement
Call an attorney when…
Denials, coverage fights, deadlines.
- Advises on legal rights
- Handles litigation
- Result: settlement or judgment
FAQ
Plain answers from a New Hampshire Insurance Appraiser
Short answers about how appraisal works, what it costs and when it’s the wrong move.
What does a New Hampshire Insurance Appraiser do?
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work through the differences with the insurer’s appraiser and, if needed, present open items to a neutral umpire.
Is an appraiser the same as a public adjuster?
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When does it make sense to call?
When coverage has been accepted, you have the insurer’s itemized estimate, and the gap to your contractor’s number is meaningful — often more than about 10% or several thousand dollars.
Is the award binding?
On the amount of loss, generally yes, once two of the three panel members sign. That’s why the file should be complete before appraisal is demanded.
What does it cost?
Each side usually pays its own appraiser and half of the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Do you cover my town?
Yes. We work in all 10 New Hampshire counties, from Seabrook to Pittsburg.
Guides
Short reads for owners holding a short check
Practical guides from New Hampshire Insurance Appraiser on policy language, documentation and timing.
 7 min read
Ice Dams and Roof Snow Load: Building a New Hampshire Claim That Holds Up
Meltwater backing up under shingles and framing straining under a heavy winter are two different claims. Here’s how to document each so the estimate covers what actually happened.
 6 min read
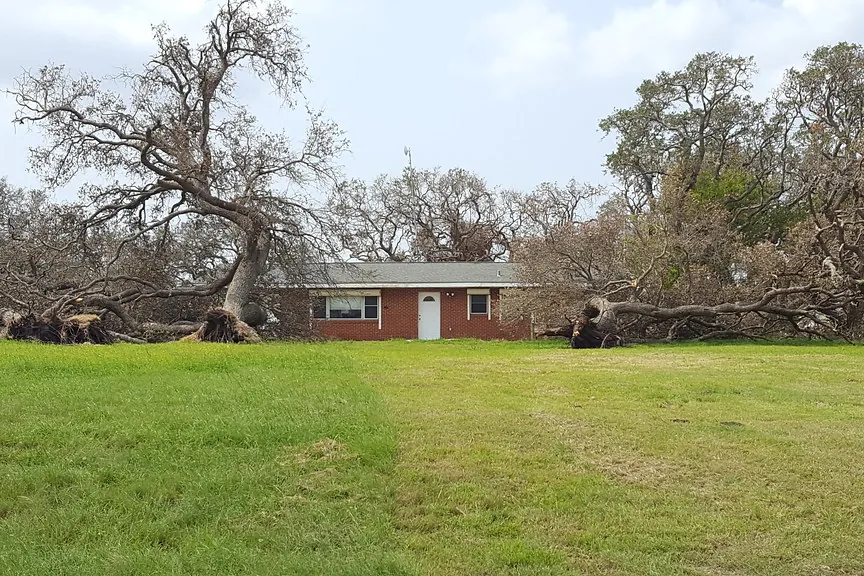
After the Nor’easter: Documenting Storm and Tree Damage the Right Way
A nor’easter can leave a pine through the porch roof and a dozen smaller problems you won’t notice for weeks. Good records from the first day keep both in the claim.
7 min readAppraisal Clause, Lawyer or Public Adjuster: Sorting Out Who Fits Your NH Claim
Appraisers, public adjusters and attorneys solve different problems. Matching the help to the kind of dispute you have saves time, money and frustration.
Start here
Bring your claim file to a New Hampshire Insurance Appraiser
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing.
- Call or text+1 (844) 537-1427
- Emailinfo@newhampshireinsuranceappraiser.com
- HoursMon–Fri, 8am–6pm ET
- CoverageAll 10 counties, 234 cities and towns